A single RICS Red Book valuation can determine whether a mortgage is approved, how much inheritance tax an estate pays, or whether a property sale proceeds at the agreed price. Yet fewer than one in ten property owners or solicitors who dispute a figure know the structured, evidence-led process for challenging it without triggering alarm among lenders, buyers, or beneficiaries.
Understanding how to challenge a Red Book valuation without damaging a sale, refinance or probate matter requires more than simply believing the number is wrong. It demands a clear grasp of the legal framework, the margin of error courts accept, and the practical steps that preserve transaction momentum while still putting your case forward.
Key Takeaways
- Courts accept a margin of error of roughly plus or minus 5% for standard residential property and up to 15% or more for unusual assets; a challenge that only moves the figure within this bracket is unlikely to succeed as a negligence claim [1][7]
- A valuation can only be successfully challenged on the basis of process failure, inappropriate comparables, ignored planning issues, or incorrect assumptions, not merely because a different figure is preferred [5][10]
- The safest approach in live transactions is to commission a second Red Book-compliant valuation and use both reports as evidence in structured negotiation, not immediate litigation [3][4]
- In probate matters, factual errors such as mis-stated floor areas or incorrect tenure are the most defensible grounds for challenge and are least likely to trigger HMRC scrutiny or beneficiary disputes [8][11]
- The 2025 RICS Red Book Global Standards require valuers to clearly document their methodology and assumptions, giving challengers a concrete checklist against which to test any report [3]
What a Red Book Valuation Actually Is
Before mounting any challenge, it helps to understand what the document being questioned is required to contain. A Red Book valuation is a formal written opinion of value produced by an RICS Registered Valuer in compliance with RICS Valuation, Global Standards, commonly known as the Red Book. The latest edition became effective on 31 January 2025 and applies to all RICS members providing valuation services in transactional, lending, and probate contexts [3][4].
The 2025 edition restructured several core requirements. Notably, the former VPS 5 was split into VPS 3 (valuation approaches and methods) and VPS 5 (valuation models), reinforcing the expectation that valuers must clearly explain the methods and inputs they use [3]. This structural change is significant for anyone mounting a challenge: it means every compliant report should contain a documented rationale for how the valuer arrived at the figure, not simply a conclusion.
The report must set out the basis of value, scope of work, key assumptions, any special assumptions, and any limitations. Where a valuation is commissioned for mortgage lending, the scope is typically defined by the lender's instructions. For probate, it is governed by HMRC guidance and the terms agreed with the executor. Understanding the scope is the first step in any challenge, because a valuation can only be criticised fairly within the terms it was asked to address [3][15].
For properties with specific characteristics, shared ownership interests, Help to Buy equity loans, or charity-owned assets, the applicable basis of value and assumptions will differ from a standard freehold transaction. A shared ownership valuation or a Help to Buy valuation each carries its own set of RICS-prescribed assumptions, and any challenge must acknowledge those specific parameters.
The Legal Framework: Margin of Error and the Bolam Test
The courts have developed a well-established framework for assessing whether a Red Book valuation is legally deficient. Two concepts sit at its heart: the acceptable bracket and the Bolam test.
The Acceptable Bracket
Courts and commentators have consistently held that a valuation is not negligent simply because it differs from another professional's opinion. The recognised margins are:
| Property Type | Accepted Margin of Error |
|---|---|
| Standard residential property | Approximately plus or minus 5% |
| One-off or unusual properties | Approximately plus or minus 10% |
| Exceptional or complex assets | Up to plus or minus 15% or more |
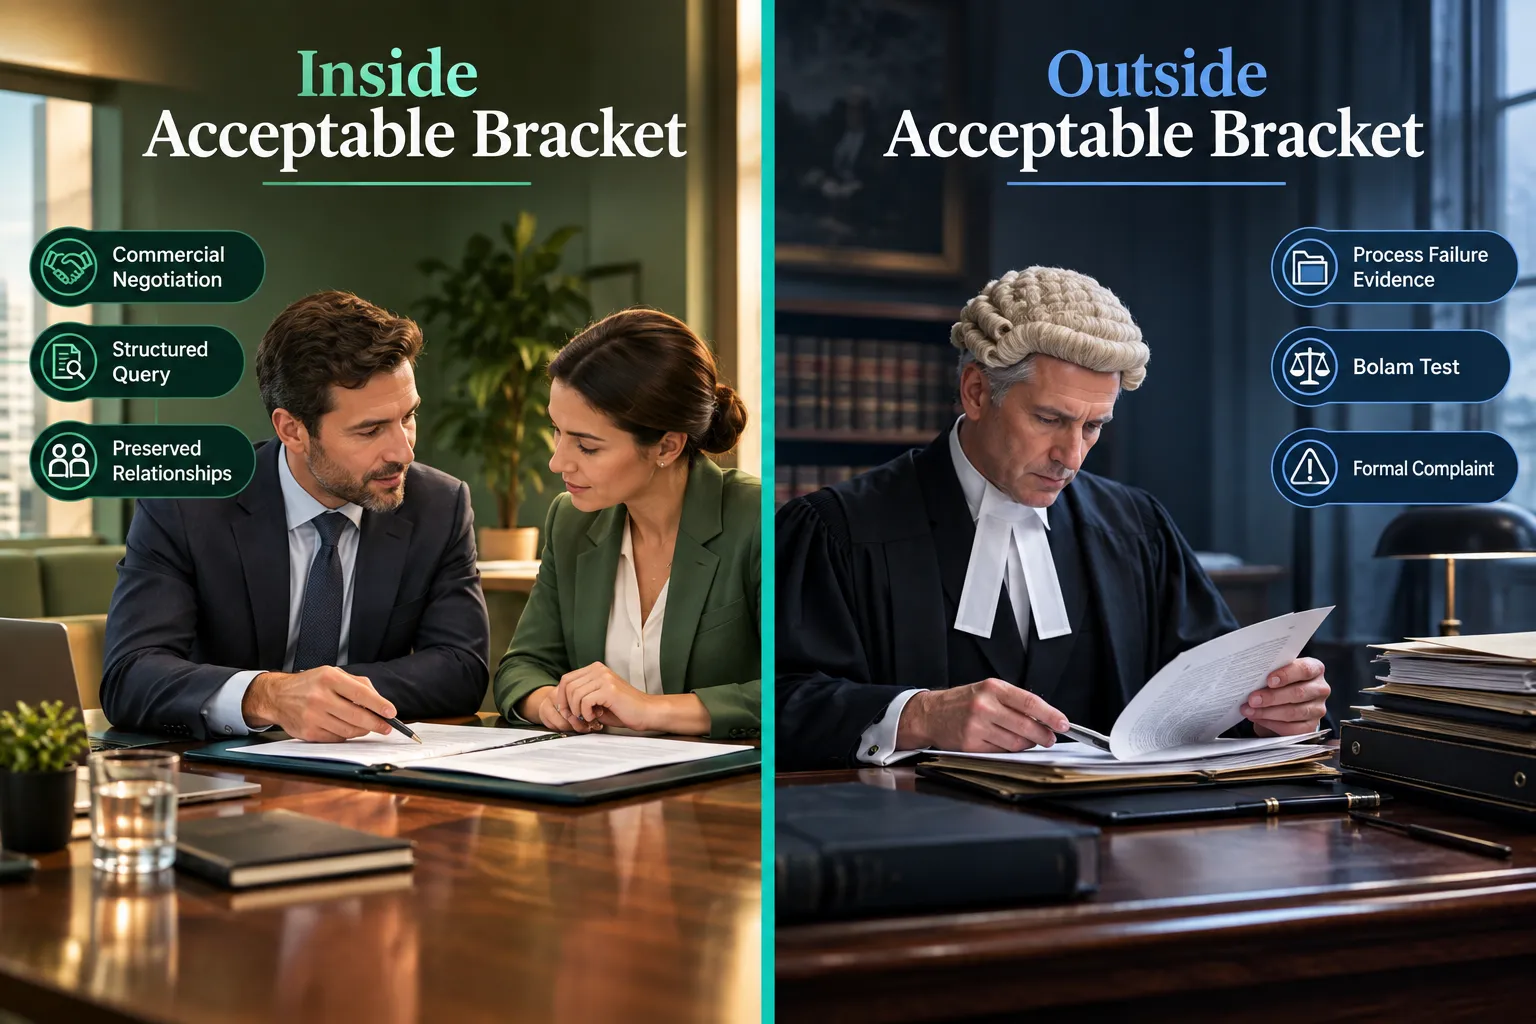
A challenge that only moves the figure within this bracket will not support a negligence claim and is better framed as part of commercial negotiation rather than formal legal proceedings [1][13]. This is a critical point for owners and solicitors to absorb: if the disputed figure falls within the bracket, the appropriate route is negotiation, not litigation.
The Bolam Test and Bratt v Jones
Even where a valuation falls outside the acceptable bracket, negligence is not automatically established. The Court of Appeal judgment in Bratt v Jones (2 May 2025) confirmed that a claimant must prove two things: first, that the valuation fell outside the acceptable bracket; and second, that the valuer failed to exercise due professional skill and care under the Bolam test [5][10].
A valuation that is wrong is not necessarily negligent. The court must be satisfied that at least one step in the valuer's process fell outside what a respectable body of professional opinion would regard as acceptable.
This distinction matters enormously in practice. It means that challenges should concentrate on specific process failures, an inappropriate choice of comparables, failure to account for a material planning constraint, or an incorrect assumption about tenure, rather than simply asserting that the figure is too low or too high [5][10][12][13].
The burden of proof does not shift to the valuer simply because the court finds the figure outside the permitted bracket. It remains with the claimant throughout to demonstrate a breach of the Bolam duty [12]. This clarification, reinforced in Gowling WLG's analysis updated in 2026, strongly discourages casual accusations of negligence in sale or refinance negotiations.
The case of Hope Capital v Alexander Reece Thomson [2023] EWHC 2389 (KB) adds a further caution for those challenging valuations in a refinance context. The High Court found nil loss for the lender even where the valuation was criticised, illustrating that even a successful challenge may not result in recoverable loss if the damage was caused by other factors such as borrower misconduct or market collapse [6][14]. Parties should therefore be careful not to assume that identifying an overvaluation automatically justifies halting a refinance or pursuing the valuer.
How to Challenge a Red Book Valuation Without Damaging a Sale, Refinance or Probate Matter: A Practical Framework
The goal in most live transactions is not to destroy the valuation, it is to correct it, adjust it, or negotiate around it while keeping the deal intact. The following framework achieves that.
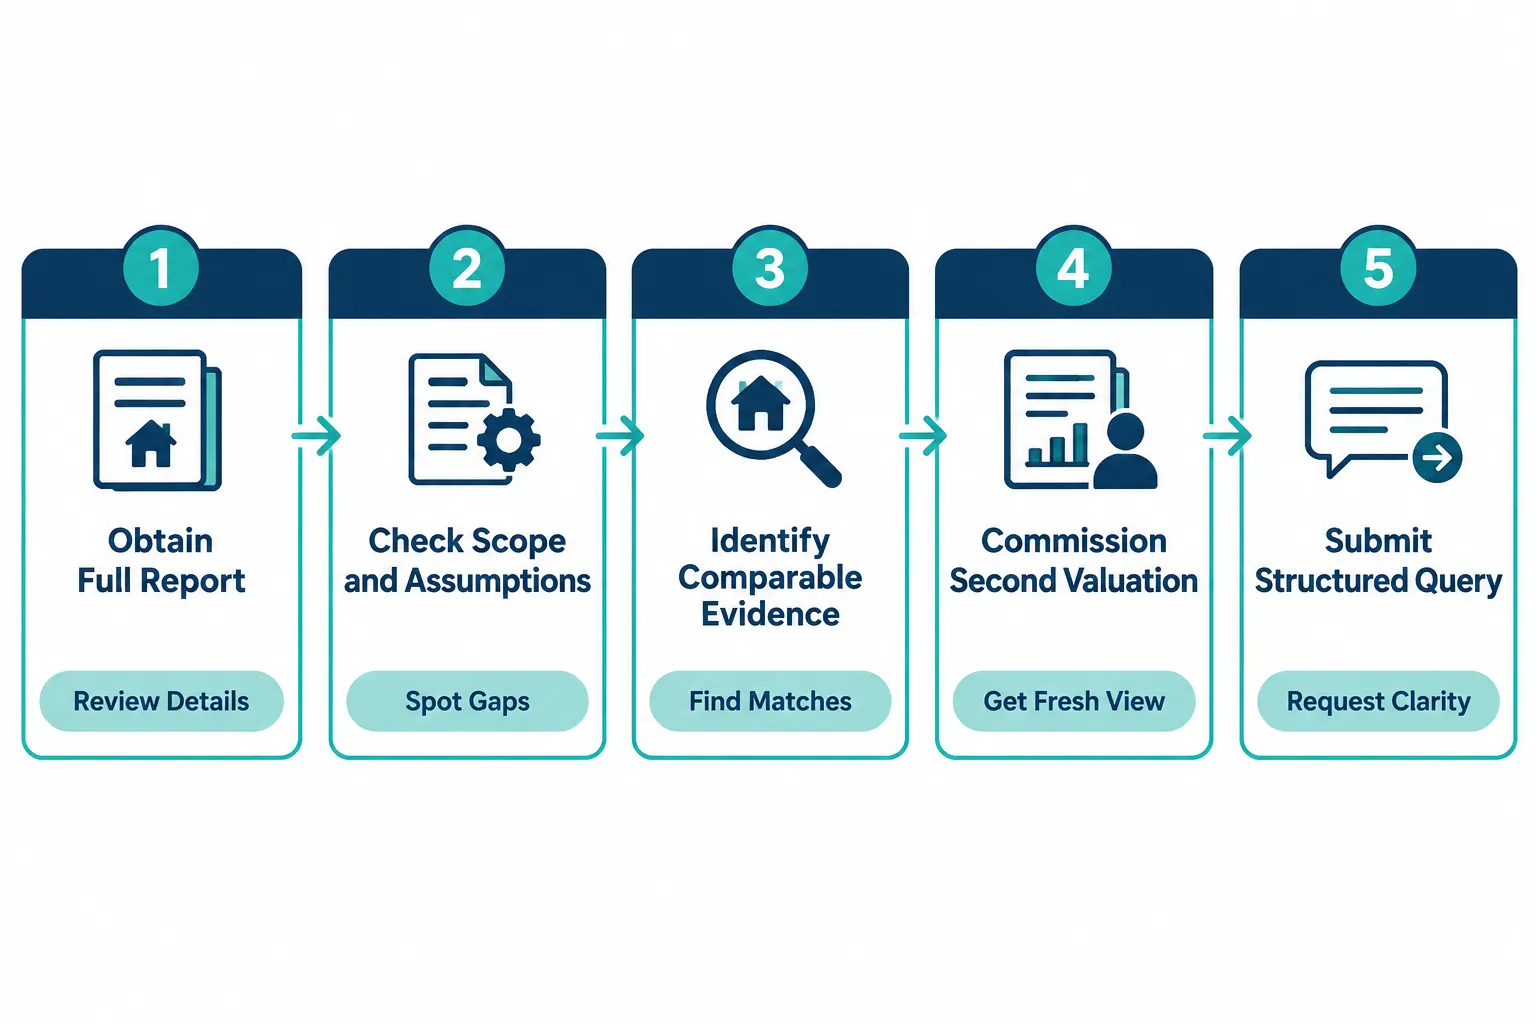
Step 1: Obtain and Read the Full Report
Request the complete valuation report, not just the headline figure. Many disputes arise because parties react to a number without reading the assumptions, scope limitations, and comparable evidence on which it is based. A property valuation report in Red Book format will set out the basis of value, the inspection date, the comparables used, and any caveats. Read all of it before forming a view.
Step 2: Check the Scope and Assumptions
Compare what the valuer was asked to do against what the report says was done. Ask:
- Is the basis of value correct for the purpose (market value for a sale, RICS Red Book for a mortgage, open market value for probate)?
- Are the special assumptions clearly stated and appropriate?
- Does the scope of work match the instructions given by the lender, solicitor, or executor?
If the scope was narrower than the purpose required, or if a special assumption was applied without disclosure, this is a documented process failure that can be raised without threatening the transaction.
Step 3: Identify Specific Technical Errors
The most defensible challenges focus on verifiable facts rather than subjective judgements. Common grounds include:
- Incorrect floor area, a mis-stated gross internal area directly affects value and is objectively measurable
- Wrong tenure, leasehold versus freehold, or an incorrect remaining lease term, can materially alter the figure
- Inappropriate comparables, sales used as evidence that differ significantly in location, condition, or specification without adequate adjustment
- Ignored planning constraints or permissions, a material planning restriction that was not reflected, or a permitted development right that was overlooked
- Market conditions not properly reflected, particularly relevant where there has been a significant market movement between the inspection date and the report date
Each of these represents a potential failure of process, not merely a difference of opinion about value [5][10][13].
Step 4: Commission a Second Red Book-Compliant Valuation
Where the grounds for challenge are substantive, the most effective tool is a second opinion from an independent RICS Registered Valuer. This second report should be produced to the same Red Book standard and address the same basis of value and scope as the original. The two reports can then be placed side by side in negotiation, allowing the parties to see exactly where the methodologies diverge.
This approach preserves the working relationship between all parties and avoids the alarm that a formal negligence allegation would create among lenders, buyers, or beneficiaries [3][4][12].
Step 5: Submit a Structured Written Query
Rather than telephoning the valuer or making informal complaints, put the challenge in writing. A structured query should:
- Reference the specific section of the report being questioned
- Cite the factual error or process concern clearly
- Attach supporting evidence (comparable sales data, Land Registry records, planning portal extracts)
- Request a written response within a defined timeframe
This creates a documented record and demonstrates good faith. It also gives the valuer the opportunity to correct a genuine error without the matter escalating [3][8].
Step 6: Use RICS Complaints and Escalation Procedures
If the structured query does not resolve the matter, the next step is the firm's internal complaints procedure, followed if necessary by a referral to RICS. RICS has a formal regulatory process for complaints about members, and a well-evidenced complaint about process failure is taken seriously. Litigation should be reserved for cases where there is robust evidence of substandard practice and demonstrable financial loss [12][5].
Specific Considerations for Sale, Refinance and Probate Contexts
Sale Transactions
In a sale, a low mortgage valuation is the most common trigger for a challenge. The lender's valuer may have used comparables from a different micro-market or failed to account for recent improvements. The key is to act quickly, most mortgage offers have a defined validity period, and to use a second valuation or a targeted query rather than alleging negligence, which can cause a buyer to withdraw [1][5].
Refinance Matters
A refinance challenge is particularly sensitive because the lender has a direct interest in the outcome. Hope Capital v Alexander Reece Thomson confirms that even where a valuation is criticised, recoverable loss may be limited if other factors contributed to the lender's position [6][14]. The practical approach is to present a second Red Book-compliant valuation alongside a clear analysis of the comparable evidence, framed as a request for reconsideration rather than a formal complaint.
Probate Matters
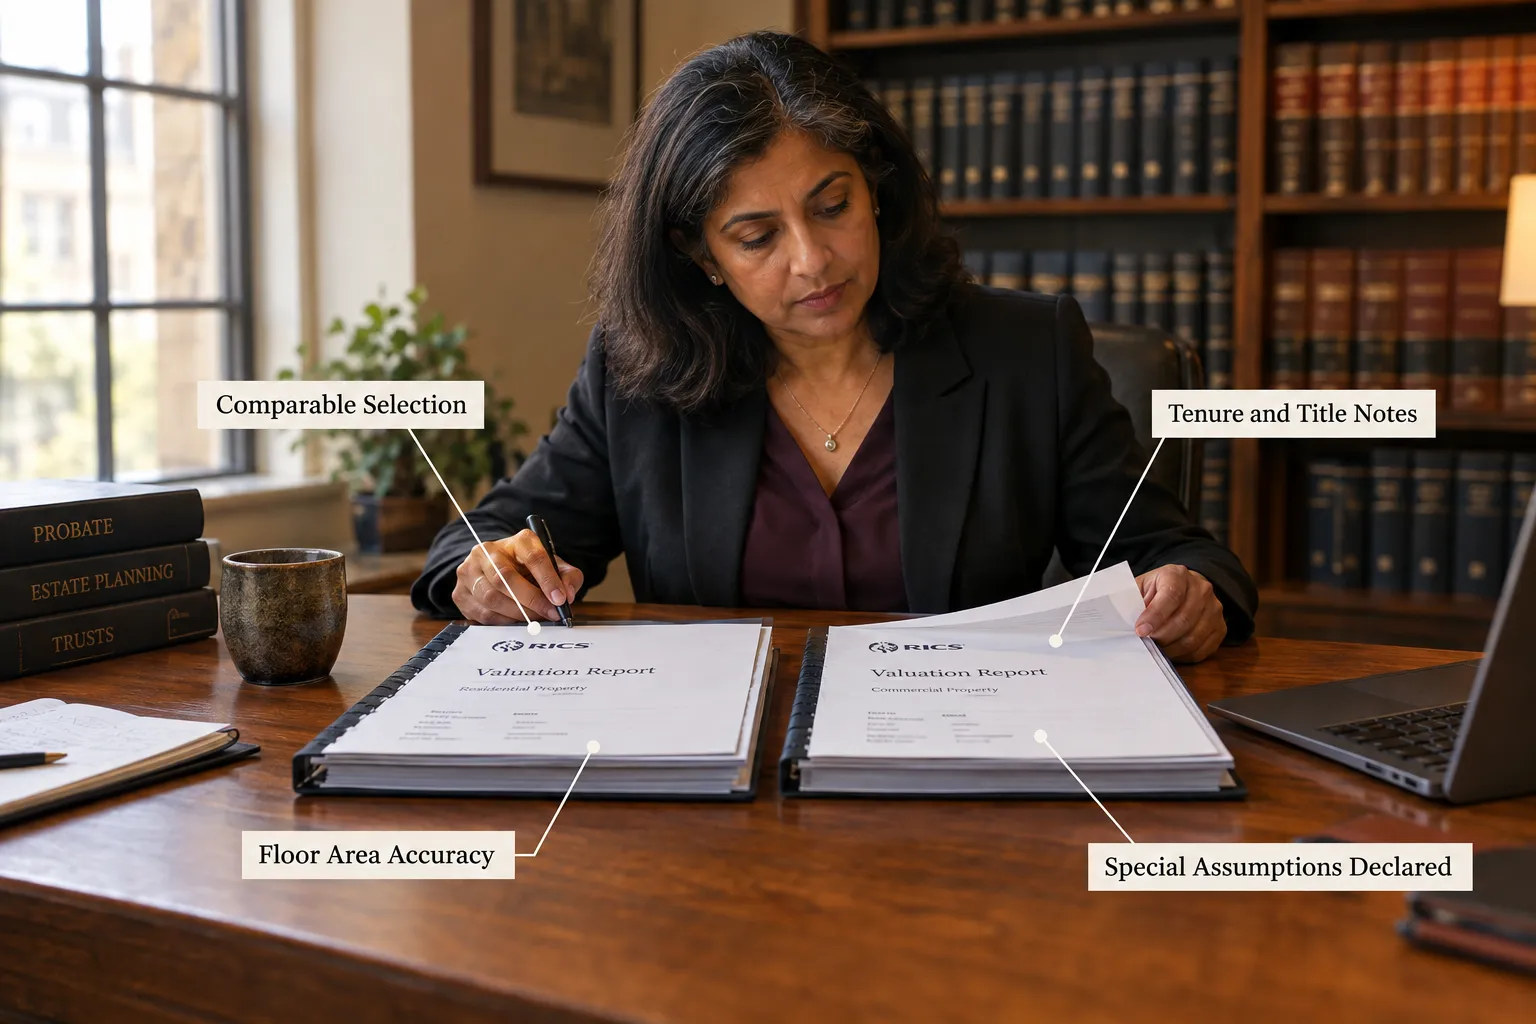
In probate, the stakes are different. A valuation that is too high increases the inheritance tax liability; one that is too low may attract HMRC scrutiny. Growing judicial attention to how valuers handle unusual properties and incomplete information means that probate challenges carry real weight when grounded in factual errors [7][8].
The safest approach is to highlight specific, verifiable discrepancies, incorrect floor area, wrong tenure, outdated comparables, and request a Red Book-compliant review. For estates involving divorce property valuations or matrimonial valuations, the same principle applies: ground the challenge in documented facts, not a competing number without evidential support [8][11].
Executors should also be aware that HMRC has its own valuation office and may challenge a figure independently. A well-documented challenge process, supported by a second Red Book valuation, is far more defensible in that context than an informal dispute.
What Not to Do When Challenging a Valuation
Avoiding the following mistakes is as important as following the steps above:
- Do not allege negligence without evidence of process failure. An incorrect figure alone is not enough under the Bolam test [10][12].
- Do not challenge a figure that falls within the accepted margin of error through formal legal channels, it is unlikely to succeed and may damage relationships [1][13].
- Do not make informal or verbal complaints that leave no paper trail and give the valuer no formal opportunity to respond.
- Do not instruct a second valuer to produce a higher or lower figure without giving them the same scope and basis of value as the original, a report prepared on different terms will not be a valid comparator.
- Do not delay. In sale and refinance contexts, time is critical. A challenge that is not resolved before exchange or completion may be overtaken by events.
Conclusion
Challenging a Red Book valuation without derailing a sale, refinance or probate matter is entirely achievable, but only when the challenge is built on evidence, structured correctly, and proportionate to the grounds available.
The legal framework established through Bratt v Jones and reinforced by the 2025 RICS Red Book Global Standards makes clear that a successful challenge requires proof of process failure, not merely a preference for a different number [3][5][10]. The accepted margin of error means that many disputes are better resolved through negotiation and a second independent valuation than through formal complaint or litigation [1][13].
Actionable next steps for owners, solicitors, and executors:
- Obtain the full Red Book report and read the scope, assumptions, and comparable evidence before reacting to the headline figure
- Identify specific, verifiable technical errors rather than general disagreement with the conclusion
- Commission a second Red Book valuation from an RICS Registered Valuer on the same scope and basis
- Submit a structured written query with supporting evidence, giving the original valuer a formal opportunity to respond
- Escalate through RICS complaints procedures only where the query is not resolved and there is clear evidence of process failure
- Reserve litigation for cases with robust evidence of substandard practice and demonstrable, recoverable loss
A well-executed challenge protects the transaction, preserves professional relationships, and puts the best possible evidential case before lenders, buyers, beneficiaries, or HMRC, without the collateral damage that comes from making allegations that cannot be sustained.
References
[1] Valuers Negligence 14 5 Within The Margin Of Error – estatesgazette.co.uk
[3] Red Book Global – rics.org
[4] Red Book – rics.org
[5] Valuers Negligence – carruthers-law.co.uk
[6] Valuers Negligence Before The Court Of Appeal – dwfgroup.com
[7] Sdb78tf72n – ora.ox.ac.uk
[8] Sava Law Note Mar 24 – sava.cdn.cloud-infra.co.uk
[10] Valuation Negligence Bratt V Jones – gatehouselaw.co.uk
[12] Valuers Negligence Before The Court Of Appeal – dwfgroup.com
[13] Valuers Negligence 14 5 Within The Margin Of Error – estatesgazette.co.uk
[14] Valuers Negligence Before The Court Of Appeal – dwfgroup.com