Fifty-four out of sixty-three economists polled by Reuters between 12 and 14 October now expect the Bank of England to raise interest rates on Thursday. If they are right, it will be the first increase in Bank Rate since August 2023, reversing a run of six consecutive cuts that only ended just before Christmas 2025. For anyone buying, selling or remortgaging in Kingston upon Thames and the surrounding area, the Bank of England interest rate decision 5 November 2026 house buyers are watching carries real, practical consequences this week.
This article sets out exactly what is at stake, why inflation has forced the Bank's hand, and what local buyers, sellers and remortgagers should do before Thursday's announcement lands.
Key Takeaways
- Bank Rate has held at 3.75% since 17 September 2026, but a quarter-point rise to 4% is widely expected on Thursday 5 November 2026.
- CPI inflation hit 3.5% in September, driven by transport and fuel costs linked to the Middle East energy shock, according to the ONS.
- Average five-year fixed mortgage rates have been above 6% since early October, says Knight Frank Finance.
- Nationwide's October index shows UK house prices up just 0.5% year on year, the weakest growth since January 2024, while mortgage approvals have fallen to their lowest since December 2023.
- Buyers and sellers mid-transaction should act now: lock mortgage offers, commission independent surveys and valuations, and avoid relying solely on lender figures in a softening market.
Why the Bank of England Interest Rate Decision on 5 November 2026 Matters to House Buyers
The Monetary Policy Committee held Bank Rate at 3.75% on 17 September, by a 6-3 vote. Since then, inflation data has hardened the case for a rise. The Office for National Statistics reported on 21 October that CPI inflation climbed to 3.5% in September, up from 3.1% in August and 2.9% in July. The ONS attributes much of this to higher transport costs, particularly motor fuel, amid an energy shock tied to the ongoing conflict in the Middle East.
Against that backdrop, a quarter-point rise to 4% on Thursday is now the base case among forecasters. It would mark the first increase since Bank Rate peaked at 5.25% in August 2023, before six successive cuts brought it down to 3.75% by the end of last year.
Governor Andrew Bailey has been careful to stress that a rise is "not inevitable", but markets and most economists are positioned for one. For the Bank of England interest rate decision 5 November 2026 house buyers in Kingston should treat Thursday as a pivot point for mortgage pricing, lender caution, and local transaction timelines.
What Comes After Thursday: The Forecasts
This is unlikely to be a one-off move. Several forecasters expect further tightening into 2027:
| Forecaster | Expectation |
|---|---|
| Capital Economics (Ashley Webb) | Two more quarter-point rises, reaching 4.25% by February 2027 |
| Oxford Economics (Andrew Goodwin) | Rises in November and February to 4.25% |
| Fidelity International (Conor Parle) | Rises in November and February to 4.25% |
| Barclays (Jack Meaning) | A final 25bp hike in February 2027, "conditional on the conflict in the Middle East" |
| Market pricing (Reuters, 2 November) | Three to four further rises during 2027, taking Bank Rate to 4.75-5% |
| OBR (October 2026 outlook) | Bank Rate just above 4.25% by mid-2027 |
The direction of travel is clearly upward for now, even if the pace and ceiling remain uncertain. For those exchanging contracts in the coming months, this matters more than the single Thursday decision itself.
Mortgage Pricing: What Kingston Borrowers Are Already Facing
Mortgage rates have moved well ahead of Thursday's vote. Average fixed mortgage rates are close to 6%, and the average five-year fix has sat above 6% since early October. Simon Gammon of Knight Frank Finance says persistent inflationary pressures mean mortgage rates are likely to stay elevated for a while yet.
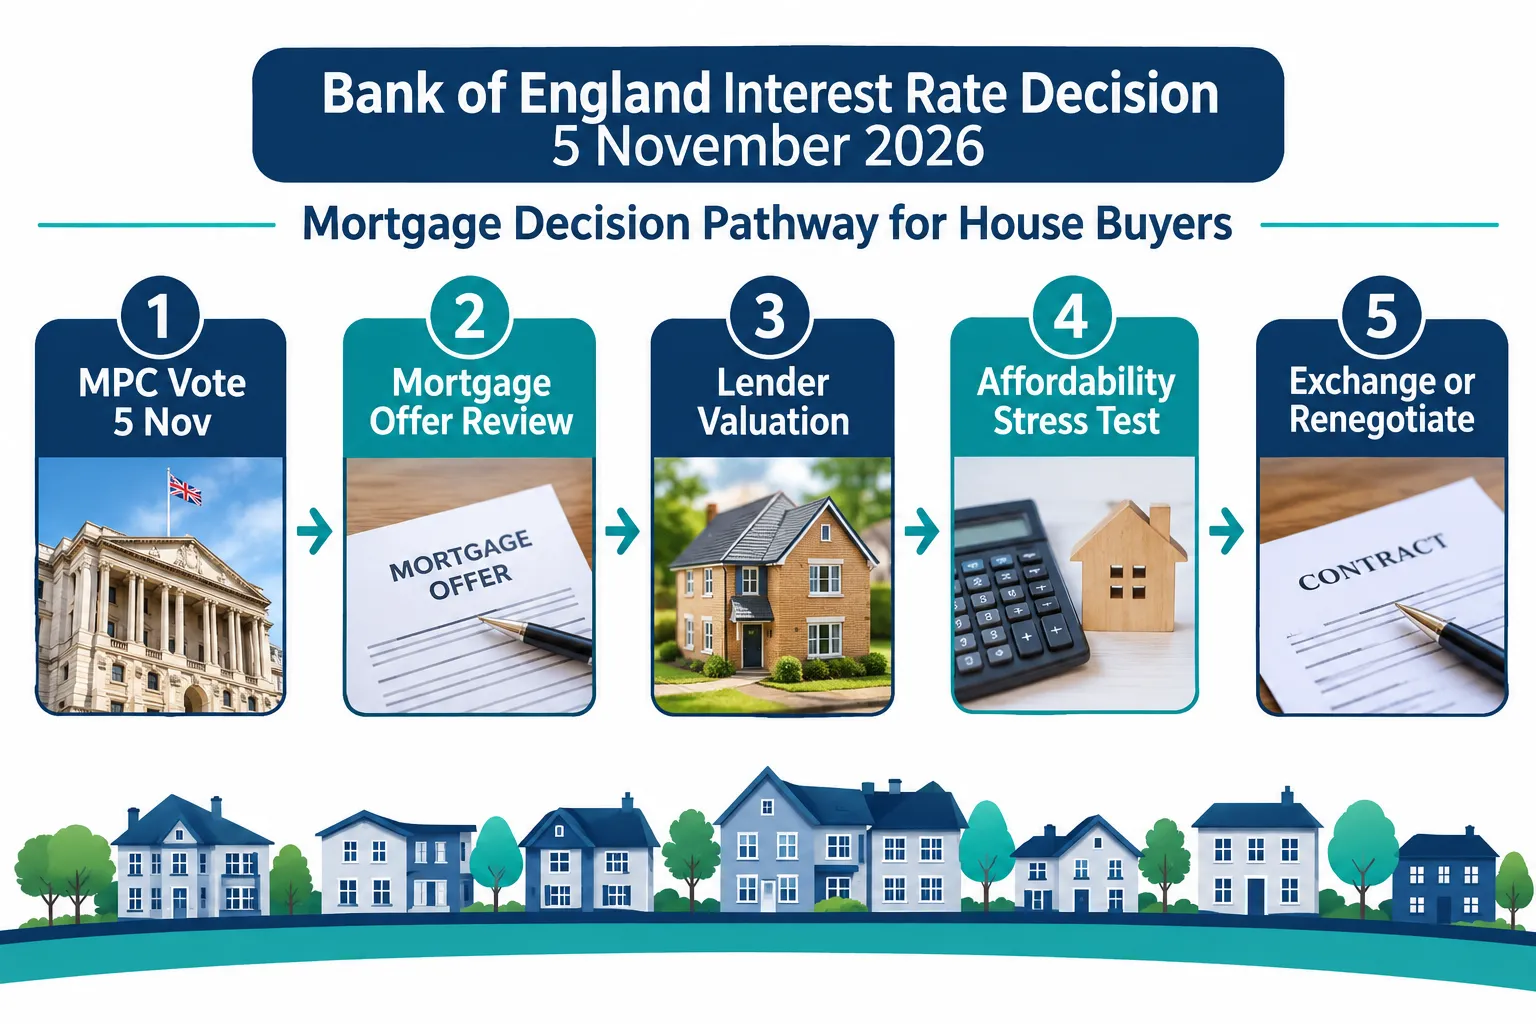
There is a practical silver lining, however. Gammon notes that most borrowers can secure a mortgage offer up to six months ahead of completion, and that offer can usually be renegotiated if rates fall before the transaction completes. Sarah Tucker of the HomeOwners Alliance puts it simply: buyers and remortgagers should be "proactive rather than reactive".
Bank of England Money & Credit data published 29 October confirms the squeeze is already visible in behaviour: house-purchase mortgage approvals fell to 53,400 in September, the lowest since December 2023, while the effective rate on new mortgages reached 4.63%.
 )
How a Rate Rise Affects Buyers Mid-Transaction
If you have an accepted offer and are waiting to exchange, a Bank Rate rise touches your purchase in three specific ways.
Mortgage offers and affordability. Lenders stress-test applications against higher notional rates. A rise to 4% may not change your existing offer, but it raises the bar for any new application or product switch, particularly for borrowers near the top of their affordability limit.
Down-valuations. Lender valuations are backward-looking and can lag a softening market. With Nationwide reporting average UK prices down 0.3% month-on-month and annual growth at just 0.5%, the weakest since January 2024, there is a real risk that a lender's valuer comes in below your agreed price, especially on properties that were marketed when sentiment was firmer.
Chain risk. Jeremy Leaf, a London estate agent, describes the current market as "highly sensitive". A single buyer or seller pulling out over rate anxiety can unsettle an entire chain, which is common in Kingston's mix of family homes and onward purchases.
This is precisely where an independent RICS Level 2 (HomeBuyer) or Level 3 (Building) survey, paired with your own valuation evidence, earns its keep. If a lender's figure looks out of step with the property's actual condition and comparable evidence, a chartered surveyor's report gives you grounds to renegotiate price rather than simply accept a lender's number or walk away. For guidance on choosing the right level of report, see this guide to building survey vs valuation survey, and for cost comparisons see building survey cost versus valuation fee.
What This Means for Sellers in Kingston
Tom Bill of Knight Frank notes that mortgage approvals are down by almost a fifth year on year, fewer buyers are reaching the finish line. Robert Gardner, Nationwide's chief economist, expects the market to "stay soft near term" but believes that "once the energy shock fades, there are good reasons to believe the market will regain momentum".
For sellers, the practical takeaway is realistic pricing. Overpricing into a market where buyer mortgage capacity is shrinking risks a longer time on market, price reductions, and chain fatigue. An independent professional valuation, rather than an optimistic estate agent guide price, gives sellers a defensible figure to negotiate from. See how this compares with lender approaches in our professional versus DIY valuation tools guide. For context on wider market trends, our recent coverage of Kingston's property market reaction to September's rate hold and Rightmove's September asking price data for Kingston sellers remain relevant.
Note also that the Autumn Budget, delivered 28 October 2026 by Chancellor John Healey, left stamp duty unchanged, so there is no fresh tax trigger distorting buyer timing this month.
Remortgagers: Don't Wait Until Your Deal Expires
Anyone coming off a fixed deal in the next six months should start shopping now rather than waiting for Thursday's outcome. Gammon's point about securing an offer up to six months ahead and renegotiating if rates move favourably applies directly here. Locking a rate now protects against further rises; if rates ease later, most lenders allow a switch to a better product before completion.
What to Do Before Thursday's Decision
Practical steps for Kingston buyers, sellers and remortgagers in the days before the MPC announcement:
- Buyers with an offer: Confirm your mortgage offer's validity window and ask your broker whether it can be renegotiated downward if rates ease later.
- Buyers nearing exchange: Commission an independent RICS survey now, not after a down-valuation surprises you. Check our checklist for house surveys in London before instructing.
- Sellers: Get a current, independent valuation rather than relying solely on agent estimates, particularly if your home has been on the market since the summer when conditions were firmer.
- Remortgagers: Start the application process now; most lenders let you lock in today's rate and switch later if a better one appears.
- Everyone in a chain: Communicate early with your solicitor and agent about timelines, as a rate move can prompt other parties in the chain to hesitate.
- If a lender valuation seems low: Request the full report and consider commissioning your own independent valuation as counter-evidence, as outlined in our red book valuation versus desktop estimate guide.
 )
FAQ
Will Bank Rate definitely rise on 5 November 2026?
Not definitely, but it is widely expected. Reuters' poll of 63 economists found 54 anticipating a rise, and Governor Andrew Bailey has said increases are "not inevitable" rather than certain.
How much could mortgage rates rise after Thursday?
Average five-year fixes are already above 6% and have been since early October, according to Knight Frank Finance. Further Bank Rate rises into 2027, as forecast by Capital Economics and Oxford Economics, could keep fixed rates elevated rather than falling back soon.
Should I delay my house purchase in Kingston because of this decision?
Most brokers advise against delaying if you have found the right property. Mortgage offers typically hold for up to six months and can often be renegotiated if rates move in your favour later, per Simon Gammon of Knight Frank Finance.
Why get an independent survey if the lender already does a valuation?
Lender valuations are primarily designed to protect the lender's security and can lag a softening market such as the one Nationwide describes for October 2026. An independent RICS survey gives you an evidence-based position to query or renegotiate a price, which is particularly valuable when approvals and prices are both under pressure.
Conclusion
Thursday's Bank of England interest rate decision 5 November 2026 house buyers, sellers and remortgagers across Kingston and north Surrey are watching will not single-handedly make or break the local market. But it will sharpen the pressures already visible in weaker price growth, falling approvals and cautious lenders. The sensible response is the same whether rates rise or hold: secure your mortgage position early, price realistically if selling, and get independent evidence on condition and value before you rely on a lender's number alone.
Kingston Surveyors provides RICS Level 2 and Level 3 surveys and independent valuations across Kingston upon Thames and south-west London. If you are buying, selling or remortgaging before or after Thursday's decision, contact Kingston Surveyors to discuss how an independent report can protect your position.