Twenty-five days. That is roughly how long homeowners in Kingston upon Thames and across south-west London have before Chancellor's officials finalise tax decisions that could reshape mansion tax bands, capital gains bills and first-time buyer support. The Autumn Budget 28 October 2026 property homeowners Kingston conversation has shifted from speculation to serious planning, and with several measures still unconfirmed, the next few weeks matter more than usual for anyone considering buying, selling or passing on a home.
This article, published by Kingston Surveyors on 3 October 2026, sets out exactly what is confirmed, what is rumoured, and what practical steps local homeowners should take before Wednesday 28 October.
Key Takeaways
- The Budget is confirmed for Wednesday 28 October 2026; several major property tax changes remain unconfirmed.
- The new Your First Home scheme (announced 29 September 2026) offers first-time buyers of new builds a 2.5% deposit, 20% government equity loan and 77.5% mortgage, but income and price caps are still to be set.
- A possible cut to the mansion tax threshold from £2 million to £1.5 million could pull many more KT postcode homes into scope from April 2028.
- Capital gains tax on residential property sits at 18%/24% today, but the Treasury is reportedly modelling rises closer to income tax rates.
- Stamp duty and council tax reform has been ruled out; a 10% inheritance tax levy for social care remains an unconfirmed rumour.
Autumn Budget 28 October 2026: Confirmed Measures Versus Rumours
Separating fact from speculation is essential before the Autumn Budget 28 October 2026 property homeowners Kingston discussions intensify further this month. The table below summarises the current position.
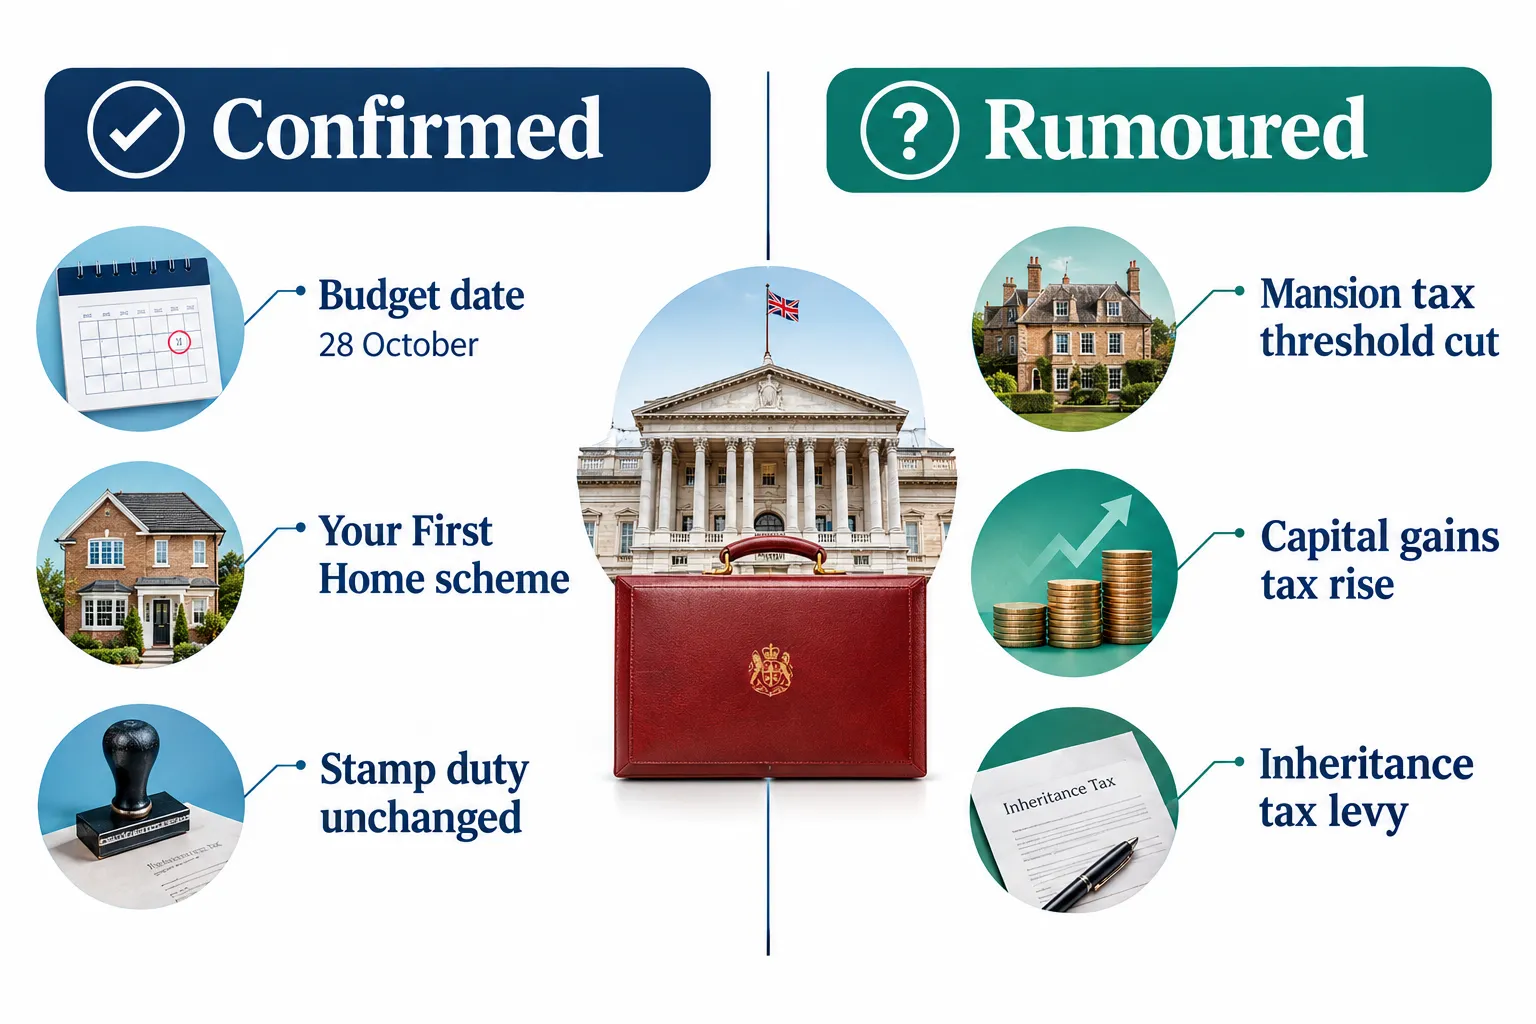
| Measure | Status | Detail |
|---|---|---|
| Budget date | Confirmed | Wednesday 28 October 2026 |
| Your First Home scheme | Confirmed, details pending | Announced 29 September 2026; caps to be set at the Budget |
| Mansion tax | Announced, threshold unconfirmed | £2m charge due April 2028; £1.5m threshold reported |
| Capital gains tax | Rumoured increase | Currently 18%/24%; Treasury reportedly modelling rises |
| Stamp duty/council tax merger | Ruled out | Burnham says it "won't be happening" |
| Inheritance tax levy | Rumoured | 10% social care levy; government says "no plans" |
Market conditions form the backdrop to all of this. Nationwide's 1 October 2026 index put the average UK house price at £274,251, with annual growth of just 0.8% and London up only 0.4%. The average two-year fixed mortgage rate stands at 5.93%, and the Bank Rate is 3.75%, with the next decision due 5 November 2026, a week after the Budget. For wider context on how south-west London buyers have been reacting to borrowing costs, see our recent coverage of the Kingston upon Thames property market and the Bank of England rate hold.
Mansion Tax and Why Kingston Homeowners Should Pay Attention
The mansion tax is arguably the measure with the sharpest local relevance. As announced, it would apply an annual charge from April 2028 to homes valued above £2 million, affecting an estimated 165,000 properties nationally. However, reports suggest the threshold could be cut to £1.5 million, which would increase the number of affected homes to around 277,000.
Many larger family homes in KT postcodes, particularly in sought-after roads near the river, Richmond Park and the better-regarded school catchments, sit in the price bracket where a lowered threshold could bite. Without stating specific local figures, it is fair to say that a meaningful number of Kingston properties could move from "unaffected" to "liable" purely because of where a banding line is drawn, not because the home itself has changed.
This is precisely where an independent RICS valuation becomes important. If a mansion tax is introduced with banding based on property value, the accuracy of that valuation directly affects the annual charge a homeowner pays. A desktop estimate or an online algorithm cannot capture the nuances that push a property above or below a threshold, things like a loft conversion, a damaged roof, or an unmodernised kitchen. For homeowners near the margin, a professional opinion of value matters. Our guide on Red Book valuation versus desktop estimates explains the difference in evidential weight between the two approaches.
Capital Gains Tax, Base Costs and Probate Valuations
Capital gains tax on residential property currently sits at 18% for basic-rate taxpayers and 24% for higher-rate taxpayers. The Treasury is reported to be modelling increases that bring CGT closer to income tax rates, though nothing has been confirmed. If rates do rise, the accuracy of a property's "base cost", the value used to calculate gain, becomes far more financially significant than it was when rates were lower.
"An independent valuation isn't just paperwork, it's the evidence base that determines what you owe, whether that's mansion tax, capital gains, or inheritance tax."
This is where retrospective and probate valuations earn their keep. If a property was inherited, gifted, or has an unclear acquisition value, a formal valuation establishes a defensible figure that HMRC is more likely to accept without challenge. Our article on retrospective valuation for London properties covers how this works in practice, and homeowners dealing with estate matters may also find our guide to divorce and probate-related property valuation useful for understanding the broader evidential standards courts and HMRC expect.
Stamp Duty, Council Tax and Inheritance Tax: What's Off and On the Table
Some clarity has already emerged. Burnham has confirmed that replacing stamp duty and council tax with a single annual property tax "won't be happening", a reassurance for anyone worried about a wholesale overhaul of property taxation mechanics.
Less settled is inheritance tax. Rumours persist of a 10% levy on estates to help fund social care, though the government maintains it has "no plans" for such a measure. For homeowners with larger estates, including those with second properties or buy-to-lets, this remains one to watch rather than act on prematurely.
First-Time Buyers, New Builds and the Importance of Snagging Surveys
The Your First Home scheme is the most concrete new policy affecting buyers. Under the plan, eligible first-time buyers of new-build homes from participating developers put down a 2.5% deposit, take a 20% government-backed equity loan (interest-free for an initial period) and secure a 77.5% mortgage. Household income caps and local property price caps are still to be confirmed at the Budget, and developers are required to contribute financially.
Industry reaction has been mixed. NHBC chief executive Paul Turner called it "a welcome boost for the industry," while Emma Toms of the New Homes Quality Board urged a statutory new-homes quality code so taxpayer-backed homes meet consistent standards. Professor Joe Nellis of MHA warned that demand-side support could feed through to higher prices without a corresponding increase in supply.
For anyone buying under this scheme, a thorough snagging survey on a new-build is essential, taxpayer backing does not guarantee workmanship quality. Our comparison of building survey versus valuation survey options and our overview of risk-checking new builds in the current construction market are useful starting points before completion.
Landlords: Timing Disposals Around the Budget
Landlords face a particular dilemma. With CGT rate increases under consideration, some may be tempted to accelerate a planned sale before 28 October. However, no change has been confirmed, and acting purely on rumour carries its own risk. A more measured approach is to obtain an up-to-date, RICS-compliant valuation now, so that if rates do change, the landlord has a clear, evidenced snapshot of value at a known date, useful for calculating any gain accurately regardless of which rate eventually applies.
Checklist: What to Do Before 28 October
- Establish current value. Commission an independent valuation, particularly if your home is near the £1.5 million or £2 million mansion tax thresholds.
- Gather base-cost evidence. Locate purchase documents, improvement invoices and any prior valuations relevant to CGT calculations.
- Review estate planning. If inheritance tax rumours concern you, speak to a solicitor rather than reacting to speculation alone.
- Hold off on rushed sales. Avoid selling purely to beat an unconfirmed tax change; confirm the detail first.
- New-build buyers: book a snagging survey. Especially important for anyone using the Your First Home scheme.
- Check mortgage timing. With the next Bank Rate decision on 5 November 2026, review fixed-rate options before and after the Budget.
- Keep records organised. Whether for mansion tax banding, CGT or probate, documentation is your strongest defence against disputed figures.
For a broader sense of how local sentiment is shifting, see our recent coverage of Rightmove asking price data and what it means for Kingston sellers.
Frequently Asked Questions
When is the Autumn Budget 2026?
The Autumn Budget is confirmed for Wednesday 28 October 2026.
Is the mansion tax threshold definitely £1.5 million?
No. The mansion tax above £2 million is announced for April 2028, but a reported cut to £1.5 million is unconfirmed and could change at the Budget.
Will stamp duty and council tax be merged into one tax?
No. The government has said this "won't be happening."
Is capital gains tax on property definitely rising?
Not confirmed. The Treasury is reported to be modelling increases closer to income tax rates, but no decision has been announced.
What is the Your First Home scheme?
A scheme for first-time buyers of new-build homes involving a 2.5% deposit, a 20% government equity loan, and a 77.5% mortgage, with caps to be confirmed at the Budget.
Should I get a valuation before the Budget?
If your property is near a possible mansion tax threshold, has unclear base costs for CGT, or forms part of an estate, an independent RICS valuation now provides useful evidence regardless of what is announced.
Conclusion
The Autumn Budget 28 October 2026 property homeowners Kingston story is still being written, and much of it depends on decisions not yet made public. What is clear is that homeowners near key thresholds, particularly the possible £1.5 million mansion tax line, stand to be affected by banding decisions that an accurate, independent valuation can help clarify. Landlords should resist rushed decisions based on rumour, while first-time buyers exploring the Your First Home scheme should prioritise quality checks on any new-build purchase.
Kingston Surveyors will publish a follow-up analysis once the Budget details are confirmed on 28 October. In the meantime, homeowners wanting clarity on current property value, base costs, or probate evidence can review our guide to chartered surveyors in Kingston or browse the latest blog posts for ongoing Budget coverage.
Autumn Budget 2026, Kingston upon Thames property, mansion tax threshold, capital gains tax property, Your First Home scheme, RICS valuation Kingston, first-time buyers new build, stamp duty reform, inheritance tax rumours, landlord CGT timing, probate valuation London, south-west London housing market